LIFESTYLE
Giving Teenagers Pocket Money: When It Helps and When It Hurts
Giving teenagers pocket money works when you name the costs it covers and talk through the choices. Silent cash, with no limit and no job, is where harm starts.

Handing a teenager cash every week feels like the obvious money lesson, and you hope they will learn to wait, compare prices, and live inside a limit. Sometimes that happens. Sometimes the cash becomes another household bill, and nobody has to choose.
Giving teenagers pocket money does harm when the amount shows up on a set day, nobody names what it covers, and you replace it as soon as it is gone. It helps when the amount stays fixed, a short list of costs moves onto your teen, and you talk when a choice goes wrong. The cash is the prop. The list and the talk are the lesson.
This page covers the pattern that backfires, how to set what the money pays for, whether chores should earn a wage, the skills worth practicing on a real week, and when a part-time job does more than the allowance.
What Is Pocket Money Supposed to Teach?
Pocket money and an allowance are the same tool under two names: a set amount you give on a schedule so a teenager can practice spending and saving while the mistakes are still small. The Consumer Financial Protection Bureau’s money guide for teens and young adults treats that practice as one piece of a larger job, with you close enough to coach and far enough to let a small mistake stand.
Teens are ready to earn, save, plan, compare what they buy, understand a loan, and keep personal details private. You are already teaching those habits on weeks you never say the word money. A bargain hunt, a treat you splurge on, or a birthday you plan shows how you think, and your teenager is watching.
Use the strength you already have. If you like comparing prices, shop one purchase out loud. If you like a plan, write the week down together. Independent decisions are the milestone to watch for: a teenager who can set a goal, look up the missing fact, and follow through is using the same skill the allowance is supposed to build.
How Can Giving Teenagers Pocket Money Go Wrong?
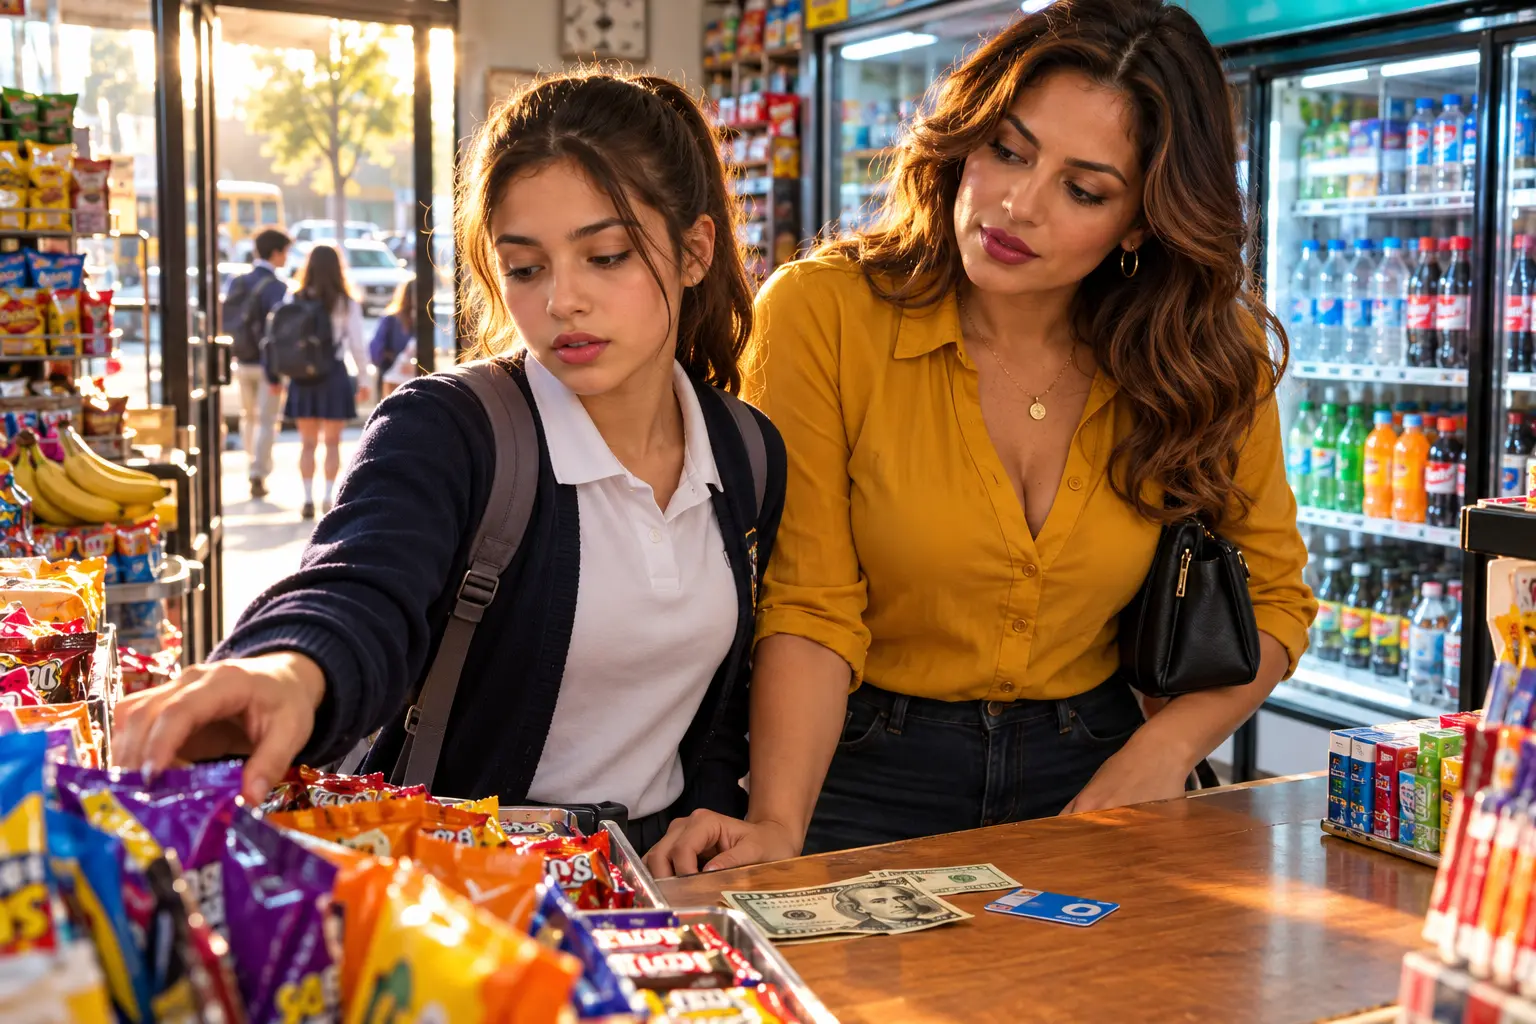
The trouble starts when the money feels guaranteed. Lewis Mandell, an economist who led the Jump$tart tests of high school seniors, expected an allowance to teach budgeting, then watched students who received one score worse, with the weakest scores among students whose allowance did not depend on chores. Those tests also connected an allowance with staying out of paid work, which removes the practice a paycheck gives.
A silent transfer creates a second problem. If your teen never hears why the grocery bill moved or what the phone plan costs, the weekly cash has nothing to attach to, and they learn the amount rather than the tradeoff. An allowance can still be a safe sum to spend, including on something they later regret, as long as you leave the regret in place.
WHERE POCKET MONEY GOES WRONG
- The schedule: Money arrives whether or not anyone made a plan for it.
- The silence: Nobody says which costs the cash is supposed to replace.
- The rescue: You add more money in the same week they overspend.
- The chore wage: Daily housework happens only when you pay for it.
Any one of those can be fixed without cancelling the allowance. Mandell has said an allowance with no strings “sets up a notion of entitlement,” and you can see that pattern when a top-up feels like a right. The rest of this page is the counter: a written list, a real conversation, and a week you do not refill.
Money Talk at Home and Teen Confidence
Parents argue about the amount, and the amount is the smaller piece. Kids whose parents have frequent talks with them about money are much more likely to call themselves knowledgeable about managing it: 46 percent, against 14 percent when those talks are rare, in T. Rowe Price’s Parents, Kids and Money Survey. That is what the kids said about themselves, not a scored test, and it still tells you which households are handing over language along with cash.
Open talk at home had the largest link to financial confidence in a 2024 study of New Zealand adolescents, ahead of pocket money and ahead of a job during the school term. Pocket money still lined up with higher confidence. It was not the main event. Boys in that sample reported higher financial confidence than girls, which is a reason to give a daughter the same money talks you give a son, not a shorter version.
You do not need a lecture for this to count. Compare two boxes at the store, show a bill next to last month’s bill, or ask what they would skip if this week’s money is already gone. The allowance gives you something concrete to discuss, and the discussion is what they can reuse when you are not in the room.
What Should Pocket Money Cover?
Set the list before you set the number. A dollar a week for each year of age is easy to remember, and it ignores what things cost where you live and which bills you are actually handing over. What it covers is the decision. The dollar figure is just the total of that list.
Write the costs down, then stop paying them on the side. In this example, a 15-year-old takes over weekday snacks at about $8 and one outing with friends at about $12, so the pocket money is $20, paid on the same day each week. If you still buy the snacks and the outing, the $20 is extra spending money, not practice.
| Cost | A clear split |
|---|---|
| School lunch | You keep paying, unless you have moved lunch onto their list on purpose |
| Basic school clothes | You keep a simple wardrobe, or you put a set clothing sum inside the allowance and say so |
| Phone line | You can keep the plan and have them pay overages from pocket money |
| Snacks and drinks out | Theirs |
| Outings with friends | Theirs |
| Game add-ons and small apps | Theirs |
| Gifts for friends | Theirs, from the same pot |
Some families switch a teen to a monthly sum so the budget looks more like adult bills. Four weeks of the example above is $80, and only if you mean four weeks. Say which costs sit inside that month. If money is tight, shrink the list before you drop the lesson: two costs, a small fixed sum, and no mid-week rescue still teach more than a large amount you cannot keep paying.
Should Teenagers Get Paid for Chores?
Daily chores are the rent for living in the house. Dishes, laundry, and a turn at the trash are not a job, and paying for them trains a teenager to price a task before they will do it. Extra work is a different category. Washing the car, a deep clean before guests, or a weekend of yard work can be paid, because those jobs sit outside the ordinary round.
Family chores are more about the responsibility of being part of a community, not about hitting up Mom or Dad every time the dishwasher needs emptying.
Beth Kobliner, President’s Advisory Council on Financial Capability
The bureau puts earning in plain words: a teen can earn through an allowance or by doing jobs for the family or for other people. Keep the allowance as the money for the agreed list, and let extra jobs be how more money shows up. Tying the whole allowance to chores fits only when the paid work is that extra work. If every dish has a price, the price becomes the reason the dish gets done.
Six Money Skills to Practice With Pocket Money
You do not need a course night. One skill in a real week is enough, and the allowance is the prop. The six lines below are the bureau’s own starters. Pick one action for this month and leave the others until the first one is a habit.
| Skill | The idea in plain words | One move this month |
|---|---|---|
| Earning | Money can come from an allowance or from jobs for family or other people | List two paid jobs outside daily chores |
| Saving | Put money aside for something you want | Move a slice to savings on payday, before any spending |
| Planning | You have to choose how to spend what you have | Write the week’s costs before the week starts |
| Shopping | Compare prices and features before you buy | Check two sellers on the next purchase over an amount you set |
| Borrowing | A loan is paid back, plus more, because of interest | Use a written IOU if you lend them money |
| Protecting | Important personal information stays private | Turn on account alerts and keep codes off group chats |
Saving is the habit to lock in first, because it happens before the spending decisions get loud. The other five get easier once a slice of the money is already gone to a goal.
How to Split a Week of Pocket Money
- On payday, move savings out before anything is spent. The bureau’s guidance is to save 10 percent of earnings once a teen has steady pay, and you can start that same slice on pocket money.
- Leave the rest as spending money for the list you agreed on.
- If a goal costs more than one week, write the price and the date on the same note as the list.
- At the end of the week, look at what is left for a few minutes. Ask what they would repeat and what they would skip.
On the $20 example, 10 percent is $2 set aside and $18 left for snacks and the outing. The point of the small slice is the order, savings first, not the size of the pile. A goal they can name will beat a jar with no label.
How Should a Loan From You Work?
You will probably be their first lender. Treat a small shortfall as a loan with terms, not as a mood. Say they are $25 short of a concert ticket that goes up in price tomorrow. You can lend the $25, and they pay it back from the next two weeks of pocket money, written down where you both can see it.
- The amount: Write what you lent, not a round number you will forget.
- The dates: Name the payday each repayment comes from.
- The cost: If you want interest to feel real, add a dollar or two on a small loan and say that borrowed money costs more than the price tag.
Skip the loan when the purchase can wait. A parent who lends for every want is back to topping up, with extra steps. Interest on a bank or card loan is the same idea at a higher price, which is why this kitchen-table version is worth doing while the sum is still $25.
How to Protect a Teenager’s Money Details
KEEP CODES AND ACCOUNT DETAILS PRIVATE
- The PIN: A parent on a custodial account is not the same as a friend who knows the PIN.
- The code: One-time text codes are a key to the account, not a favor for a group chat.
- The card: A photo of the front and back of a card is enough for someone else to spend.
- The alert: Turn on purchase alerts so a charge they do not recognize shows up the same day.
A debit card takes the money at once, and a credit card bills it later, which is why a balance check before paying matters more once the money is digital. Have them open the app, read the balance, then pay. Credit in a teenager’s own name is an adult product at most banks, so a debit card on an account you can see is the practice step.
What to Do When Pocket Money Runs Out Early
The lesson is the empty stretch of the week. If the outing money goes to delivery food by Wednesday, the weekend plan waits. Do not replace it. Putting the cash back deletes the cheapest mistake they will get to make while they still live with you.
Talk after the sting, and keep it short. Ask what they would skip next time, mention a purchase you regret, and thank them for saying they are stuck. Then leave the plan as it is. A speech in the moment mostly teaches them to hide the next one.
Step in when the pattern changes, not when one week is messy. Hidden spending, money borrowed from friends they cannot repay, or pressure to buy something risky is a different conversation from a bad snack run. You still do not have to fund the snack. You do need to know what is going on, and you need a time to look at the account together without an audience.
When Does a Part-Time Job Teach More Than Pocket Money?
A job during the school term teaches something the Saturday cash does not. In that New Zealand study, a term-time job had about twice the link to financial confidence that pocket money did. A holiday job did not show a clear link. Pocket money was common in the group. A job in term time was not, which is why helping them find a few hours of real work is worth it even if the allowance stays.
The first paycheck is the moment to read gross pay beside take-home pay. Taxes come out before the money hits the account, and the stub is the map of those deductions. Sit with one stub, line by line, and ask where each line goes, including school funding and other public costs they already use.
When their pay covers the list you handed over, the automatic allowance can stop. You can still pay for a cost you chose to keep, such as the phone line, without restarting a weekly stipend. The shift is from “here is this week’s money” to “here is the budget you now run,” with you nearby for the questions a first job actually raises.
Frequently Asked Questions
Should Pocket Money Be the Same for Every Sibling?
Siblings can receive different amounts when the costs they cover are different, and you should be able to say that reason out loud. A younger teen with fewer outings does not need the same sum as an older teen who pays for transport. What should match is the rest of the deal: the same money talks, the same unpaid daily chores, and the same refusal to refill a blown week.
Is a Debit Card Better Than Cash for a Teenager?
A debit card is better for seeing the spending and worse for feeling it, so it works if your teenager checks the balance before paying. Debit moves the money at once, which is why a quick look at the balance stops a lot of surprise spending. Keep a parent on a custodial account if the bank requires it, and do not treat that as permission for a friend to know the PIN.
When Should You Stop Giving a Teenager Pocket Money?
Stop the automatic payment when pay from a job covers the costs you handed over. You can still pay for something you chose to keep, such as the phone line or school supplies, without restarting a weekly stipend. The new arrangement is that they run the budget, and you stay available for questions about the first paycheck, taxes, and a savings slice.
What If Two Homes Disagree on Pocket Money?
Agree on which costs the money covers, even when the two amounts cannot match, so snacks are not paid twice or missed entirely. A short note both homes can see is enough. If the dollars differ, keep the same rule against mid-week top-ups, or one home becomes the place that erases mistakes made in the other.
Should You Match the Money Your Teenager Saves?
A match helps a named goal and turns into extra pocket money if you pay it every week with no cap. Set a ceiling, name the goal, and add your share when they reach the amount they promised. Once they have a job and real bills, a stronger target than a snack match is an emergency cushion of at least three months of living expenses, the backup described in the bureau’s saving guidance.
When the first paycheck arrives, sit with the stub and read gross pay next to take-home pay before you change the allowance. The FDIC’s Money Smart for Young Adults lessons walk through that stub, a spending plan, and the cost of borrowing, and one module on the week the job starts is enough. Until that stub exists, the list on the fridge and the week you leave empty are the practice.
Disclaimer: This article is an educational guide to family decisions about pocket money and is informational only. It is not financial, tax, or legal advice, and it is not a plan for your teenager’s accounts, loans, or job. Talk with a qualified financial counselor, or with your bank or credit union, before you open an account, co-sign, or lend more than you can afford to lose. Figures, program names, and rules in this guide reflect the sources reviewed and can change.

Another IndiGo Radome Splits After a Normal Lucknow Landing

Apple Will Make Full Disk Access an Explicit Mac Grant

Chainalysis AI Traced the Bitget Hack in 10 Minutes

Yapily Sits Out Open Banking Deals After Turning a Profit

Google’s Gemini 4 Argon Goes to Cyber Defenders First

BMW’s Heated Seat Retreat Taught Automakers Which Fees Survive

Nashville Votes for a Dolly Parton Airport It Has Not Named

Tesla Burns AI Cash While SpaceX Sends the Invoices

Copilot’s Election Problem Shifted From Errors to Silence

John Ternus Debuts a $2,099 Foldable and Holds iPhone 18
-
 AUTO3 years ago
BMW’s Heated Seat Retreat Taught Automakers Which Fees Survive
-
 ENTERTAINMENT2 months ago
Nashville Votes for a Dolly Parton Airport It Has Not Named
-
 NEWS2 months ago
Tesla Burns AI Cash While SpaceX Sends the Invoices
-
 NEWS3 years ago
Copilot’s Election Problem Shifted From Errors to Silence
-
 NEWS2 months ago
John Ternus Debuts a $2,099 Foldable and Holds iPhone 18
-
 NEWS2 months ago
The Book on China’s Car Brain Still Stars Infineon
-
 TECHNOLOGY3 years ago
How to Find Saved Audio on Facebook?
-
 ENTERTAINMENT2 months ago
Dolly Parton Laid to Rest as the Public Funeral Began