BUSINESS
Micron’s 26 Take-or-Pay Deals Come With a Margin Bill
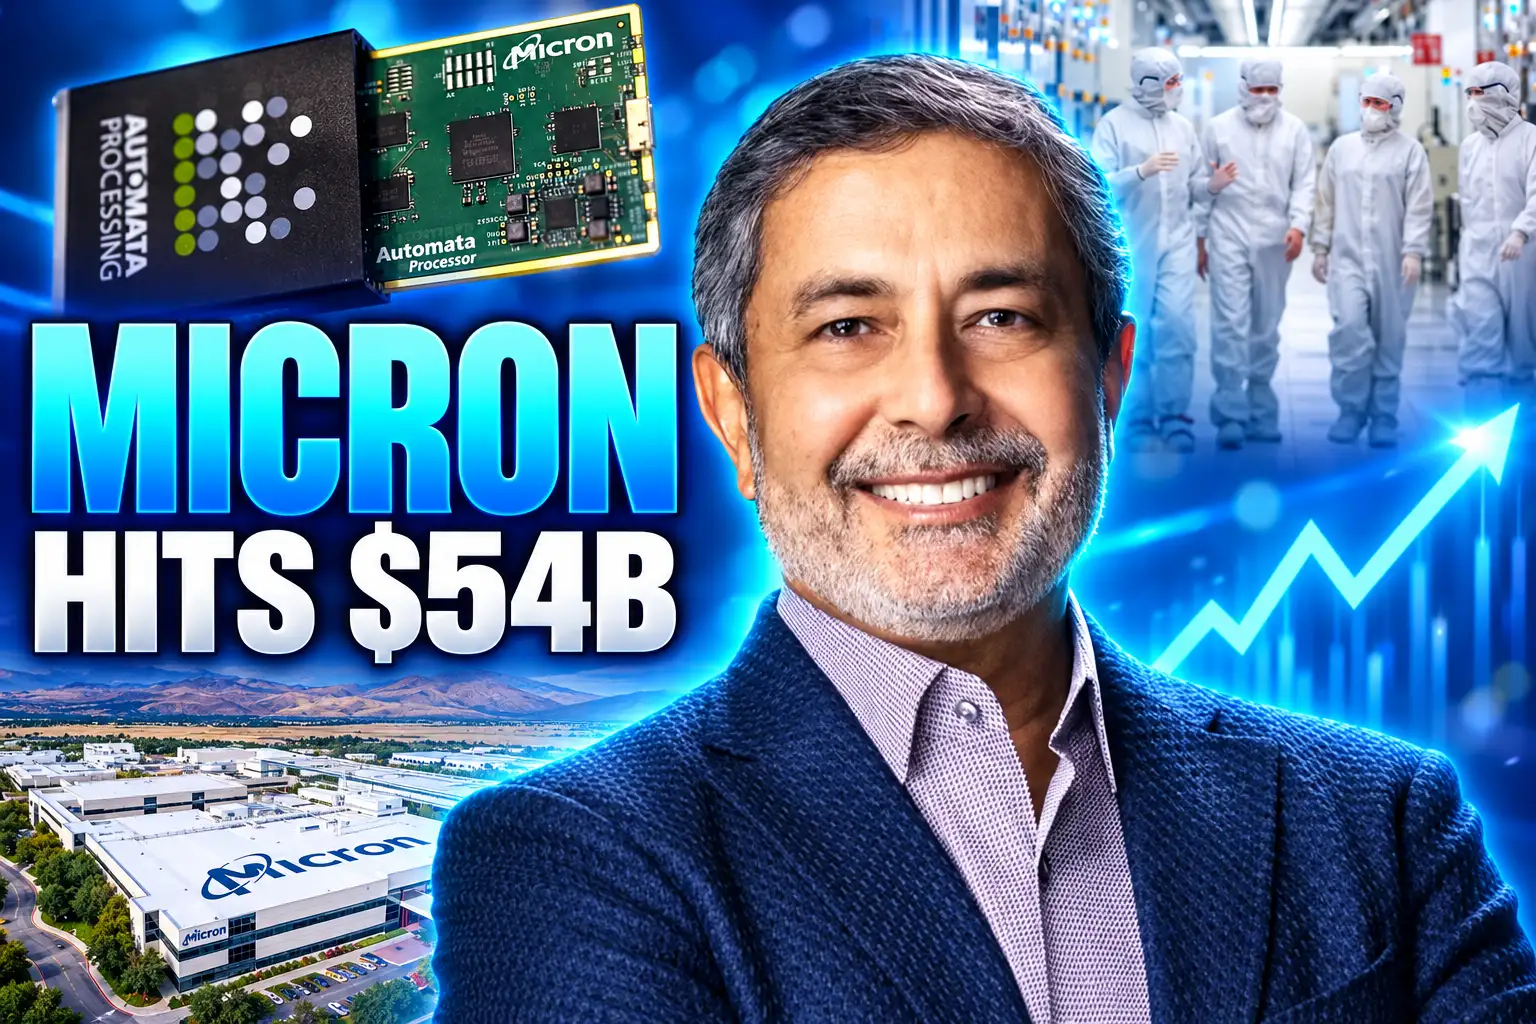
Micron’s $54.23 billion quarter came with 26 take-or-pay deals covering over 35% of 2030 sales, and a Q1 margin floor set by factory bonuses.

Micron booked $54.23 billion in fiscal fourth-quarter revenue and told investors 26 take-or-pay deals now cover more than 35% of sales through 2030. The quarter ended September 3, 2026, and the company reported after the close on September 30.
Shares closed at $1,097.39 on October 1, up 3.03% from $1,065.11, about 285% above the $285.25 finish at the end of 2025. The tape treated the print as confirmation of a bet already in the price: lock customers in for years, then live with the first bill.
Micron Just Booked a $54 Billion Quarter
The company had guided to about $50 billion of revenue, plus or minus $1 billion, and non-GAAP earnings of $31 a share, plus or minus $1. It printed $54.23 billion and $33.42. Analysts had been near $51 billion on the top line. Fiscal 2026 revenue was $133.19 billion, up 256% from $37.38 billion, and non-GAAP earnings were $75.52 a share, up 811% from $8.29.
Non-GAAP gross margin reached 87.0%, up 210 basis points from 84.9% in the third quarter and more than 40 points above the 45.7% of a year earlier. GAAP margin was 86.8%. Operating cash flow was $43.97 billion in the quarter and $89.68 billion for the year. Adjusted free cash flow was $33.20 billion and $62.31 billion. Cash, marketable investments, and restricted cash ended at $73.48 billion. The board declared a $0.15 dividend, payable October 29 to holders of record on October 14.
Chairman and CEO Sanjay Mehrotra called the year a record and said fiscal 2027 should be stronger. DRAM revenue for the year passed $100 billion. Data center revenue was up fourfold. In the fourth quarter, DRAM was $39.8 billion, or 73% of sales, up 343% from a year earlier.
THE QUARTER VERSUS THE GUIDE
| Metric (non-GAAP) | Q4 FY26 | Q3 FY26 | Q4 FY25 | Q1 FY27 guide |
|---|---|---|---|---|
| Revenue | $54.23B | $41.46B | $11.32B | $61.5B ± $1.5B |
| Gross margin | 87.0% | 84.9% | 45.7% | about 86.25% |
| Diluted EPS | $33.42 | $25.11 | $3.03 | $38.15 ± $1.00 |
Those are the figures Micron uses on the call. GAAP Q1 margin is guided at about 85.95%, and GAAP Q1 EPS at $37.84, plus or minus $1.00, on about 1.15 billion diluted shares. Core Data Center revenue was $18.00 billion at a 90% gross margin. Cloud Memory, the high-bandwidth unit, was $16.28 billion at 83%. Mobile and Client was $13.11 billion at 90%. Automotive and Embedded was $6.82 billion at 84%. Data center SSD revenue was nearly $10 billion, more than ten times the year-ago quarter and over two-thirds of NAND sales. NAND prices rose about 30% in the quarter on tight supply.
Micron posted record fourth-quarter and full-year results against its own $50 billion guide and still told the Street the next margin rate would be lower. That is the hinge the rest of the call turned on.
Twenty-Six Deals Cover Over 35% of 2030 Revenue
The number Wall Street walked in with was margin. The number management spent slides on was the contract book. Micron now counts 26 strategic customer agreements through 2030, up from 16 in June, and says those deals will account for over 35% of revenue through 2030. Remaining performance obligations, valued at contractual floor prices, are about $150 billion, up from about $100 billion. Customer financial commitments rose to $32 billion from $22 billion, the vast majority in cash deposits. Ten of the 26 were signed in the fourth quarter. Some now run into 2031, and two older deals were extended a year.
The deals are take-or-pay. A customer that does not take the wafers still owes the contracted amount. Three-quarters of the expected SCA revenue has a defined pricing framework, most of it bands with floors and ceilings. The other quarter is repriced from time to time against the market. New talks that involve price are being struck off current, higher levels. COO Manish Bhatia said the DRAM bit share under SCAs is a little under that 35% mark and NAND a little over. Mehrotra still talks about getting to about half of company revenue under these contracts.
THE SCA BUILD IN 2026
- June 24, 2026: Micron reports 16 SCAs, about $100 billion of remaining performance obligations at floor prices, $22 billion of customer commitments, and coverage near 25% of projected revenue through 2030.
- September 30, 2026: The count is 26, remaining obligations are about $150 billion, commitments are $32 billion, coverage is over 35% through 2030, and some paper extends into 2031.
In one quarter the company added 10 contracts, $50 billion of floor backlog, and $10 billion of customer money. That is the wager: trade some of the spot boom for a booked floor that is supposed to outlast it.
HOW THE 26 DEALS ARE BUILT
- Take-or-pay: Customers must take the contracted volume or pay anyway, which is how Micron describes the legal core of an SCA.
- Price bands: Three-quarters of expected SCA revenue has a set framework, most of it floors and ceilings; the rest follows the market.
- Cash first: $32 billion of commitments, almost all deposits, sit in front of the wafers as a claim on future supply.
- A 50% target: Management still describes half of company revenue, or more, as the end state for this structure.
Going into the print, Creative Strategies CEO Ben Bajarin had asked whether gross margins could stay at these rates, or whether they needed to come down so the moment did not look like gouging. The contracts are Micron’s answer to that question, and they cut both ways. Floors protect the company if prices break. Ceilings protect the customer if they do not.
Factory Bonuses Hit the Next Margin Print
First-quarter revenue is guided at a record $61.5 billion, plus or minus $1.5 billion, with non-GAAP earnings of $38.15 a share, plus or minus $1.00. Analysts had been near $57 billion on revenue. Non-GAAP margin is guided to about 86.25%, 75 basis points under the 87.0% just posted. CFO Mark Murphy told analysts that dip is the floor for fiscal 2027, and that margin should climb after that even as price increases moderate.
Most of the increase in fiscal 2026 incentive compensation pertaining to manufacturing was absorbed into inventories in fiscal Q4. As a result, the effects from the sale of these higher-cost inventories principally impact fiscal Q1 gross margin.
Mark Murphy, CFO, fiscal Q4 2026 earnings call
Murphy called incentive pay “the big driver” of the gross-margin outlook. Factory bonuses for the year just ended were booked into inventory in the fourth quarter. They hit cost of goods when that material ships, which is now. Bhatia said the company also has a richer incentive plan for fiscal 2027, spread across the year. Operating expenses are expected to rise by about $2.5 billion in fiscal 2027, mainly from more R&D and more incentive pay. Non-GAAP opex in the first quarter is guided at about $2.06 billion.
So the first bill on the boom is payroll, not a price cut. That is a cleaner story for the stock than a demand scare, and it is also a reminder that 87% margin is a labor cost away from being 86%. Mehrotra said employees were rewarded “in a record fashion,” and that factory bonuses for the fourth quarter show up as production costs in the current quarter.
The Boom-Bust Pattern Those Contracts Are Built to Survive
Memory has paid for itself in spikes and then given the money back. Micron’s own non-GAAP gross margin was 40.9% in fiscal 2025 and 81.1% in fiscal 2026, a 40-point swing in a single year. Management has said that even at SCA floor prices, margins should sit well above peak quarters from any earlier cycle. The June prepared remarks put floor prices above any prior cycle in those words, and they also put many of the first ceilings near then-current calendar second-quarter 2026 market prices.
That last clause is the part of the bet the 87% quarter does not prove. A floor that is “well above” an old 40% year is not the same object as last quarter’s print. Three-quarters of SCA revenue can be boxed inside a band. The remaining quarter still floats. Mobile and Client just posted a 90% gross margin on $13.11 billion. If that rate is a spot-price print, it can move without the HBM contracts moving at all.
Over 75% of fiscal 2027 shipments are already committed, SCA and non-SCA combined. That is allocation as much as it is a cycle break. It tells you 2027 is spoken for. It does not tell you what 2029 looks like if a hyperscaler slows a build or a handset buyer walks the NAND book down to the floor.
Most of Next Year’s HBM Is Already Spoken For
High-bandwidth memory is the product that makes the shortage feed on itself. HBM revenue in the fourth quarter grew faster than the company as a whole. Micron has completed agreements for the vast majority of its calendar 2027 HBM bits, at prices well above 2026, and says that is narrowing the margin gap with conventional DRAM. HBM4 is ramping. The company is building a custom HBM4E product with Nvidia, NVHBM, for the next GPU and NVLink Fusion platforms.
Mehrotra said a large part of 2027 HBM volume is already sold, and that 2027 prices are much higher than 2026 prices. He also said memory and storage will be much tighter in fiscal 2027 and 2028 than they were in 2026. DRAM bit growth is seen in the low 20% range in calendar 2027 and 2028, after the mid-20s in 2026. HBM is expected to grow faster than conventional DRAM through 2028, which uses more wafer starts for each bit shipped.
THE 2027 BOOK MICRON SAYS IS CLOSED
- Shipments: More than 75% of fiscal 2027 bits are already under allocation or contract.
- HBM: The vast majority of calendar 2027 HBM supply is contracted at higher prices than 2026.
- SSD: Data center SSD was nearly $10 billion in the fourth quarter, over two-thirds of NAND, and on track for a fifth year of record share in that market.
- Servers: Unit growth is still seen in the high teens in calendar 2026 and 2027, with content growth a bit slower than earlier plans because supply is tight.
Bhatia told analysts the firm still has no line of sight to when supply and demand balance. Structural limits he listed include weaker bit gains from each new process node, HBM taking a rising share of wafer starts, and higher trade ratios as stacks get more complex. That is the supply side of the wager: do not build fast enough to crash the price, and hope the contracts still look smart if you guessed wrong.
What the Take-or-Pay Book Leaves Open
A floor is not a volume. Take-or-pay can collect cash on a shipment that never sits in a named accelerator. Micron did not break the 26 deals out by end market, and it did not split remaining obligations between HBM and commodity DRAM. New SCA talks are at higher prices, which means the first wave, the one with ceilings near earlier 2026 levels, is a different instrument from the paper signed this summer.
WHAT WE KNOW
- The count: 26 SCAs, over 35% of projected revenue through 2030, about $150 billion of floor backlog, $32 billion of commitments.
- The Q1 math: Revenue guided to $61.5 billion plus or minus $1.5 billion, non-GAAP margin about 86.25%, named as the fiscal 2027 floor because factory bonuses in inventory are shipping now.
- The tightness claim: Management says 2027 and 2028 will be tighter than 2026, with most 2027 HBM already priced higher.
WHAT IS UNCONFIRMED
- The downturn print: Floor margins “above any prior cycle” have not been tested by a real drop in demand.
- The mix: How much of the $150 billion is HBM that must ship into GPUs, versus DRAM a phone or PC buyer can delay.
- The capex response: Fiscal 2026 capital spending was $27.37 billion, including $10.77 billion in the fourth quarter; the company has not shown a 2028 supply wave large enough to break the shortage it is forecasting.
Overnight after the release, the stock barely moved. On October 1 it rose 3.03% to $1,097.39, still under the $1,255 high from June 25, 2026, with a market value of about $1.24 trillion. That is the posture of a name that already ran 285% this year: a beat was assumed, a 75-basis-point margin dip was explained as pay, and the contract book was treated as the reason not to fade it.
Idaho, Singapore and a Tighter 2028
The capacity that would end a shortage is late relative to the cash. The first New York fab is at a concrete-pour milestone, with initial wafers aimed at calendar 2030. Idaho’s ID1 is on track for wafer output in mid-calendar 2027, ID2 in late 2028. A Japan DRAM expansion is slated for late 2028. Taiwan’s Tongluo site is due to ship in a meaningful way in mid-2027. Singapore’s HBM packaging line is ahead of plan for early 2027, and a new NAND fab there is due in the second half of 2028. Mehrotra noted that new fabs only become meaningful a few quarters after first wafers.
That schedule is why management can say 2028 is tighter than 2026 without contradicting a $27.37 billion capex year. The bits from Idaho and Singapore arrive into a book that is already mostly sold. They do not arrive in time to refill a 2027 allocation meeting. They might arrive in time to test the ceilings on the first SCAs, or to sit behind take-or-pay invoices if a customer would rather pay than take.
Bhatia still has no line of sight to balance. The contracts run through 2030, some into 2031. The first test of the floor they bought is the quarter now under way, when last year’s factory bonuses finally show up in cost of goods and Murphy’s 86.25% either holds or does not.
Disclaimer: This article is news reporting and analysis of Micron Technology’s fiscal 2026 results and fiscal 2027 outlook, and it is for information only. It is not investment advice, a recommendation to buy or sell Micron or any other security, or a prediction of future returns. Readers should consult a licensed financial adviser or other qualified professional who can weigh their own goals, time horizon, and risk tolerance before acting on any figure here. Revenue, margin, guidance, contract, and share-price numbers reflect company statements and market data as of the dates named in the piece and may change with later filings, restatements, or trading.

Chainalysis AI Traced the Bitget Hack in 10 Minutes

Yapily Sits Out Open Banking Deals After Turning a Profit

Google’s Gemini 4 Argon Goes to Cyber Defenders First

Micron’s 26 Take-or-Pay Deals Come With a Margin Bill

Meta Turns AI Data Centers Into a $3.9 Billion Credit

BMW’s Heated Seat Retreat Taught Automakers Which Fees Survive

Tesla Burns AI Cash While SpaceX Sends the Invoices

John Ternus Debuts a $2,099 Foldable and Holds iPhone 18

Dolly Parton Laid to Rest as the Public Funeral Began

Copilot’s Election Problem Shifted From Errors to Silence
-
 AUTO3 years ago
BMW’s Heated Seat Retreat Taught Automakers Which Fees Survive
-
 NEWS4 weeks ago
Tesla Burns AI Cash While SpaceX Sends the Invoices
-
 NEWS4 weeks ago
John Ternus Debuts a $2,099 Foldable and Holds iPhone 18
-
 ENTERTAINMENT1 month ago
Dolly Parton Laid to Rest as the Public Funeral Began
-

 NEWS4 weeks ago
The Book on China’s Car Brain Still Stars Infineon
-
 NEWS3 years ago
Copilot’s Election Problem Shifted From Errors to Silence
-

 TECHNOLOGY3 years ago
Twitter Search Not Showing All Results: How to Fix it?
-
 NEWS4 weeks ago
SAP Puts Token Spend on the Same Line as Hiring